


Latest news
JPMorgan Chase is expanding its innovation economy division, adding close to 200 bankers this year, as it seeks to fill the void left by the collapse of Silicon Valley Bank and other regional lenders. The bank's U.S. startup client portfolio nearly doubled in 2023. Ashraf Hebela, head of startup banking, emphasizes that JPMorgan has always served startups, but the March turmoil accelerated client acquisition. JPMorgan has hired former SVB executives, including John China, and is leveraging its full suite of services and capital strength to compete with fintechs and other banks. While CEO Jamie Dimon acknowledges room for improvement, the bank's long history and end-to-end offerings position it well to serve startups throughout their life cycle.
With more banks and credit unions entering cannabis banking, competition is intensifying. North Bay Credit Union now offers interest-bearing cannabis accounts to differentiate itself, while other institutions like Bank Michigan and Dart Bank stick to service and reputation rather than paying interest. The number of institutions serving cannabis clients rose to 812 in Q2 2023, according to FinCEN, and pending legislation could further open the sector. Banks are weighing strategies such as lower fees, account analysis, and differentiated services to retain high-balance cannabis deposits.
Goldman Sachs' acquisition of GreenSky in 2021 was seen as a fintech success story, but just two years later, the investment bank is seeking to sell the installment-lending firm at a significant loss. The move comes as Goldman scales back its Marcus consumer banking platform. Bids for GreenSky have been lower than expected, and the sale may result in a write-down. The saga serves as a warning to fintechs about the risks of selling to large institutions, highlighting the importance of strategic alignment and the potential for reputational damage from regulatory issues.
Payment fraud is becoming increasingly severe, with businesses urging banks to enhance information sharing and joint prevention. According to the U.S. Federal Trade Commission, consumer fraud losses reached $8.8 billion in 2022, with bank transfer losses nearing $1.6 billion. Organizations like Nacha are promoting new risk management frameworks, but data sharing among banks and coordination across nearly 10,000 institutions remain major obstacles.
Payments fraud has intensified, with U.S. consumers reporting $8.8 billion in losses in 2022, a 30% increase from 2021, according to the FTC. At Nacha's Smarter Faster Payments conference, Con Edison's Frank D'Amadeo criticized banks for not doing enough to stop fraud before it reaches corporates, sparking debate. Fraudsters exploit faster payments and AI, and synthetic identity fraud is growing. Nacha is developing a new risk management framework and maintains a contact registry to facilitate information sharing among financial institutions. European banks, under PSD2, have adopted shared liability for authorized push payments, and some U.S. banks are exploring similar collaborative approaches.
Early Warning Services (EWS), which operates Zelle, announced that its new digital wallet Paze will go live in June, co-owned by seven major U.S. banks. Paze aims to simplify e-commerce payments and will initially cover 150 million Visa and Mastercard accounts. Industry experts believe that despite the trust advantage brought by its banking background, Paze still faces fierce competition in user adoption, merchant expansion, and security protection.
Early Warning Services (EWS), operator of Zelle, is set to launch Paze, a digital wallet owned by seven of the largest U.S. banks, in June with a wider rollout in the fall. Paze will automatically be loaded onto 150 million Visa and Mastercard accounts, aiming to make e-commerce payments easier for consumers and merchants. However, industry experts note challenges including adoption hurdles, intense competition from established players like Apple Pay and PayPal, and security concerns. EWS emphasizes Paze's connection to regulated financial institutions and multiple security layers, including one-time passcodes for transactions. The success of Paze will depend on winning over both consumers and merchants.
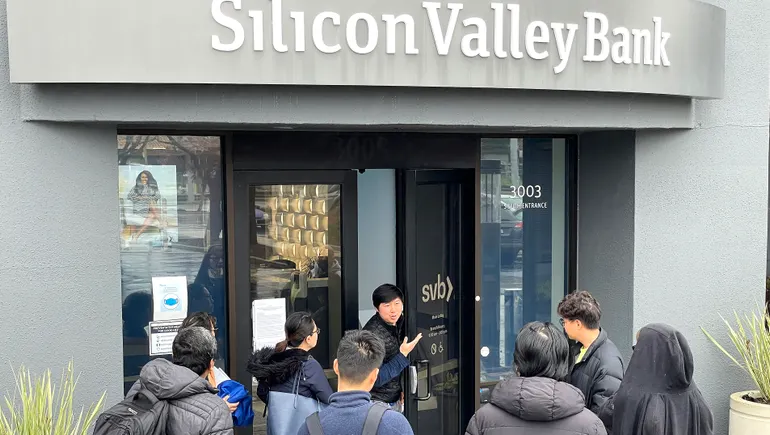
The collapse of Silicon Valley Bank (SVB) has been described as a 'reverse meme stock'—a social media-driven bank run that brought down a bank within hours. This article dissects the sequence of events, key figures, and industry impact, while looking ahead to regulatory and market developments.
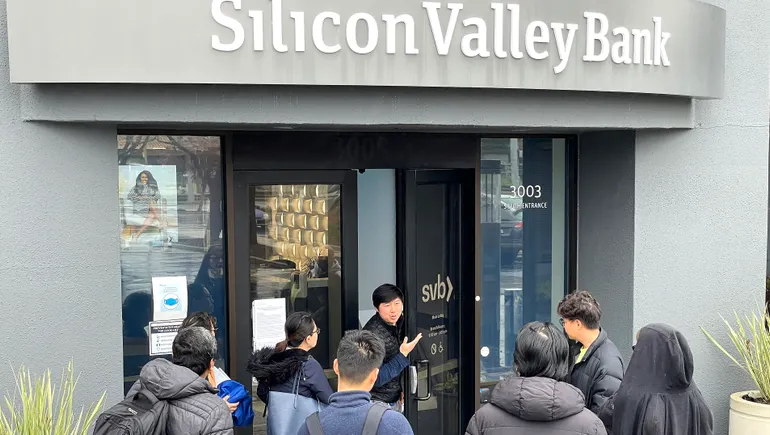
Silicon Valley Bank's collapse on March 10, 2023, was hastened by a social media-driven bank run, with depositors attempting to withdraw over $42 billion in one day. Experts say the speed of information spread and ease of digital withdrawals herald a new era of viral bank runs, where trust can evaporate in hours. Regulators backstopped all deposits, but the event has implications for how banks are valued and the role of social media in financial stability.
In early 2023, the crypto industry continued the layoff trend from 2022, but Binance plans to expand its workforce by 15% to 30% against the trend. Bitcoin slightly recovered to above $23,000, and Goldman Sachs listed it as the best-performing asset in 2023, but several banks remain cautious, while regulators have issued frequent guidance.