


Latest news
Seven Democratic senators, led by Ruben Gallego, sent a letter to CFPB Acting Director Russ Vought demanding details on the June termination of a consent order against Navy Federal Credit Union. The order, issued in November under Biden-era director Rohit Chopra, required Navy Federal to pay a $15 million civil penalty and $80.6 million in restitution for illegal overdraft fees. The senators request the full legal and factual basis for the termination, information on communications between Navy Federal and the CFPB, and details on unpaid restitution and penalty funds. They also question whether the CFPB's Office of Servicemember Affairs was consulted, contrasting the termination with the bureau's April memo prioritizing servicemembers. The letter cites concerns from former CFPB enforcement director Eric Halperin and asks how the termination aligns with the bureau's stated priorities. The CFPB under Vought has dropped several cases and reversed other consent orders, including against Bank of America and Trustmark Bank.
The Consumer Financial Protection Bureau (CFPB) has terminated its overdraft fee-related consent order against Navy Federal Credit Union, waiving any alleged non-compliance. The order, issued under former director Rohit Chopra, had required the credit union to pay over $95 million, including $15 million in civil penalties and $80 million in refunds. The termination, signed by Acting Director Russ Vought, did not provide a specific reason. Navy Federal stated it complied with all laws and believes the decision was appropriate. The CFPB also terminated an order against Fay Servicing and has recently taken similar actions to vacate other Biden-era consent orders, including those against Bank of America and Trustmark Bank, and amended an order against Wise. The agency is also undergoing significant workforce reductions and funding challenges.
The NCUA liquidated Aldersgate Federal Credit Union of Marion, Illinois, and Butler Heritage Federal Credit Union of Middletown, Ohio, within two days. Aldersgate was closed for unsafe and unsound practices, while Butler Heritage was liquidated after determining insolvency was imminent. These closures bring the total number of credit unions liquidated by the NCUA in 2025 to four. The NCUA is currently operating with a single board member after President Trump fired two Democratic board members in April.
As the political environment shifts and financial deregulation looms, 2025 offers crucial opportunities for banking professionals to network and explore business possibilities. This article highlights top conferences including America's Credit Unions Strategic Growth Conference, Finovate Fall, MoneyLIVE North America, ABA Annual Convention, The Most Powerful Women in Banking, Money20/20, The Clearing House Annual Conference, and FT Live Global Banking Summit. These events cover AI, open banking, compliance, fintech partnerships, and regulatory shifts, featuring speakers from major banks like JPMorgan Chase, Bank of America, Citi, and U.S. Bank.
Sens. Elizabeth Warren and Maxine Waters sent a letter Friday to NCUA Chair Kyle Hauptman demanding clarification on the board's legal authority to carry out agency procedures without a quorum after President Donald Trump fired board members Todd Harper and Tanya Otsuka on April 16. The lawmakers cited concerns raised in the NCUA inspector general's response, noted that the board cannot fully function with one member given statutory quorum requirements, and questioned 11 Board Action Memorandums processed since the firings. They requested a response by July 7.
Idaho Falls-based Frontier Credit Union will acquire First Citizens Bank of Butte, adding $75 million in assets and a branch to its $700 million footprint, with the deal expected to close by the end of 2025. The transaction is the sixth whole-bank acquisition by a credit union this year and the third in the past month, drawing criticism from the Independent Community Bankers of America over credit unions' tax exemption.
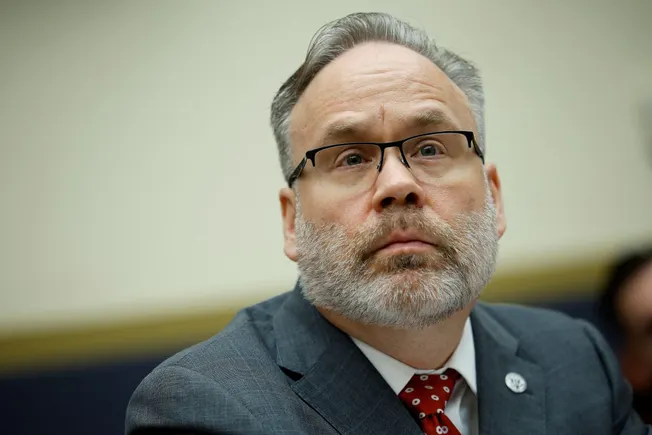
In a Brookings Institution conversation, former NCUA Chair Todd Harper said suing President Trump over his firing was a difficult decision but necessary. He described learning of his dismissal indirectly and receiving the termination email at the wrong address. Harper views the firings of NCUA and other agency board members as part of a broader strategy to target the Federal Reserve and dismantle regulatory independence. He warned that without a quorum, the NCUA board cannot implement policy changes or approve enforcement actions, and that downsizing could impair oversight of high-risk credit unions. Harper also noted weakening support for the credit union tax exemption on Capitol Hill.
The NCUA liquidated Unilever Federal Credit Union, based in Englewood Cliffs, New Jersey, on Wednesday and declared it insolvent. The credit union reported losses of $134,891 at the end of 2023 and $336,490 at the end of last year. The NCUA also issued two consent orders prohibiting two employees from participating in the affairs of any federally insured depository institution. This is the first liquidation by the NCUA in 2025. The decision comes about two weeks after President Donald Trump fired two Democratic NCUA board members, leaving Republican Chair Kyle Hauptman as the sole board member. The credit union had $46.6 million in assets and served about 1,450 members, primarily employees of Unilever's U.S. operations. Each member's account is insured up to $250,000, and creditors must submit claims by Aug. 28.
Safe Harbor Financial's new CEO Terry Mendez is prioritizing marketing and sales to grow the company's customer base and financial institution network. The fintech, which provides banking services to the cannabis industry, aims to increase its partner financial institutions from about six to 20-25 in three years. After cost-cutting measures, including reducing staff and pausing some services, Mendez is now focused on growth, despite the company's $48.3 million loss last year and going concern doubts. Safe Harbor recently hired marketing and business development leaders and formed referral partnerships with Würk and FundCanna.
Two former National Credit Union Administration (NCUA) board members, Todd Harper and Tanya Otsuka, have sued President Donald Trump and other government officials over their recent firings. The lawsuit, filed Monday, claims the removals were 'patently unlawful' and violate the Federal Credit Union Act, which requires a three-member board with no more than two from the same political party. The firings leave only Chair Kyle Hauptman on the board, preventing formal meetings or new rules due to lack of quorum. Harper and Otsuka argue the move undermines the NCUA's independence and could lead to consolidated regulation of credit unions and banks. The NCUA insures deposits for over 4,000 credit unions, safeguarding $2 trillion in assets for 142 million Americans. Senators Elizabeth Warren and Maxine Waters have also requested analysis from the NCUA Inspector General on how a one-member board can operate. The firings are part of a broader pattern of Trump removing Biden-era appointees at other independent agencies.