


Latest news
Peoples Bancorp of Marietta, Ohio, announced Wednesday it will acquire Rockville, Maryland-based Capital Bancorp in a $728 million all-stock deal. The merger will strengthen Peoples' foothold in the Washington, D.C. metro area, where it first gained a presence through its 2021 acquisition of Premier Financial. The deal is expected to close in the first half of 2027, creating a combined company with approximately $14 billion in total assets, $10 billion in loans, $11 billion in deposits, and over 150 banking locations across eight states and Washington, D.C. Capital shareholders will receive 1.11 shares of Peoples common stock for each Capital share, valuing the transaction at $43.75 per share based on Peoples' 20-day volume-weighted average closing price of $39.41 as of Tuesday. The acquisition is expected to be immediately accretive to Peoples' estimated 2027 earnings before one-time costs, with a tangible book value earnback period of less than three years. Three Capital board members will join Peoples' board after closing. This is Peoples' second acquisition of 2026, following its planned purchase of Citizens Bank of Kentucky, which received final regulatory approvals on Monday.
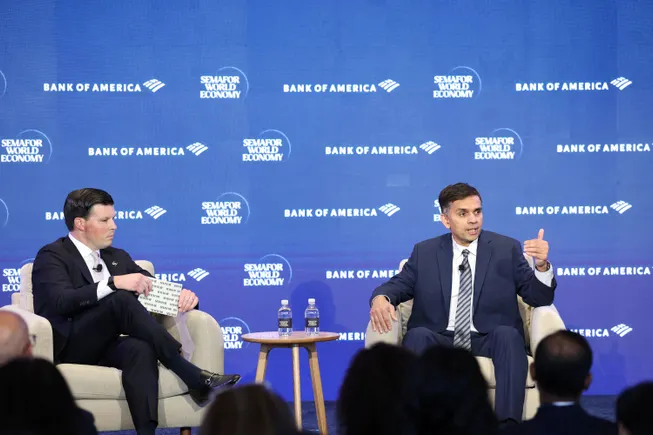
Bank of America's Technology Innovation Summit, now in its 15th year, brings together about 500 tech company founders and investors with bank leaders. According to Hari Gopalkrishnan, the bank's chief technology and information officer, the event not only helps scout partners but can also lead the bank to shift gears on tech initiatives. About one-fifth of the 7,000 participating companies have become vendors. The summit provides insights into industry trends, helps startups understand enterprise-scale implementation, and informs BofA's strategy, with AI and payments as key focuses.
Gulf Winds Credit Union, based in Pensacola, Florida, has agreed to buy Monroeville, Alabama-based Peoples Exchange Bank, marking its second whole-bank acquisition in about a month and the seventh proposed credit union-bank deal this year. The acquisition will give Gulf Winds a second location in Monroeville and a fourth in Alabama, expanding its assets to $1.75 billion. Peoples Exchange Bank has one branch and $98.6 million in assets. Gulf Winds announced last month it would buy Madison County Community Bank and rebrand as TruWorth Credit Union next spring. CEO Daniel Souers called the two acquisitions 'the first chapter of TruWorth.' Final regulatory approval is expected in mid-2027, with integration by early 2028. The pace of credit union-bank deals has slowed in 2026, with seven through the first nine months, down from 16 last year and a record 22 in 2024. The ICBA continues to urge lawmakers to end the federal tax exemption for credit unions with $1 billion or more in assets, while America's Credit Unions CEO Scott Simpson has said changes to the tax code could negatively impact how credit unions help consumers and communities.
The Federal Reserve's Office of Inspector General (OIG) issued a management alert highlighting information security risks and control deficiencies at the central bank board. The alert stems from a 2024 incident in which a departing Division of International Finance employee potentially removed classified Federal Open Market Committee (FOMC) information. The OIG learned of the incident in July 2025, a year after the employee retired. The report notes prior incidents involving the same employee in 2021 and 2023, including copying files to an unencrypted USB device and attempting to send classified information to a personal email account. The OIG found a collective lack of action across multiple divisions, unclear governance and enforcement of information security controls, and insufficient escalation. The Fed board concurred with the OIG's recommendations and plans to implement process improvements, including a new data loss prevention solution, by 2027.
Greg Keeley has departed as chief operations officer of SMBC Americas, according to an internal email from CEO Hiro Otsuka. Masahiro Yoshimura, deputy CEO of SMBC Americas, will take on responsibility for the COO organization on an interim basis, effective immediately. Keeley joined SMBC in April 2025 after seven years at TD and nearly 22 at American Express. His executive biography has been removed from the SMBC website. The move comes as SMBC pursues operational changes in the U.S., including recruiting in Charlotte, North Carolina, winding down its Jenius digital banking platform, and selling branches and assets to Axos Bank and Bank of Hope.
Circle CFO Jeremy Fox-Geen will step down in December after five years as finance chief, the company announced Friday. Fox-Geen helped lead Circle through its June 2025 IPO, which raised $1.05 billion at an approximately $8 billion valuation. He will remain CFO until December 31 or the appointment of a successor, and will receive a $1.05 million cash payment and accelerated vesting. Circle also announced a $100 million equity investment from Binance and the immediate resignation of co-founder P. Sean Neville from its board for personal reasons. TD Cowen analysts expect an orderly transition with no internal disruption.
Irvine, California-based Nano Banc failed Friday, becoming the sixth U.S. bank to collapse in 2026, the most in any year this decade. The California Department of Financial Protection and Innovation cited deteriorating financial condition, executive mismanagement, and regulatory violations. Sunwest Bank agreed to assume most of Nano's assets and deposits in a deal with the FDIC. Nano's single branch reopens Monday as a Sunwest location. The FDIC estimates the failure will cost the Deposit Insurance Fund about $114 million.
The Federal Deposit Insurance Corp. issued a prompt corrective action directive to Old Glory Bank for being 'significantly undercapitalized,' with a leverage ratio of 2.69% as of June 30. The bank must submit a capital restoration plan within two weeks and is restricted from accepting brokered deposits, paying management fees, and other activities without regulatory approval. Old Glory, which lost about $8 million in the first half of the year, is seeking to raise capital after its planned merger with a SPAC fell through when the Federal Reserve did not approve the transaction.
Valley National Bancorp, based in Morristown, New Jersey, has agreed to acquire Bluevine, a Jersey City-based small-business banking fintech, for $340 million in cash and stock. The deal, projected to close in early 2027, will bring Valley about $2.1 billion in deposits and expand its small-business customer base by 20 times. Bluevine, founded in 2013, has about 175,000 active small-business customers and provides digital banking, payments, lending, and financial management solutions. The acquisition also includes Bluevine's technology and AI capabilities, with about 180 R&D employees joining Valley. Bluevine CEO Eyal Lifshitz will join Valley as head of small-business banking. The deal consideration is 75% cash and 25% Valley stock, with expected earnings per share accretion of about 8% and tangible book value dilution of about 5% at closing. Valley executives said they do not anticipate pursuing additional acquisitions for the foreseeable future, following the recent announcement of another deal for Providence Financial Corp.
Mission Lane received conditional approval from the Office of the Comptroller of the Currency to establish Mission Lane Bank National Association, a nationally chartered credit card bank. The approval, granted five months after application, brings the fintech closer to issuing its own credit cards. The company aims to expand its customer base and footprint, offering tailored credit card products. The charter, created under the Competitive Equality in Banking Act of 1987, allows Mission Lane to originate and hold loans without partner banks. The bank must raise $35 million in initial capital within 12 months and maintain an 11% tier 1 leverage ratio for three years. Mission Lane still awaits FDIC deposit insurance approval.