


Deep Dive
来自我们记者的行业洞察
As interest rates rise, mortgage demand has fallen significantly, and several major banks have cut jobs in their mortgage departments. Industry experts point out that automation technology can optimize the lending process, helping institutions cope with volatility and avoid large-scale layoffs.
Rising interest rates have led to a sharp drop in home loan demand and refinancing, causing layoffs at banks like JPMorgan Chase and Wells Fargo. Industry experts suggest that automation in mortgage processes—such as document review, loan origination, and income calculation—can help lenders break the costly boom-and-bust staffing cycle. Mortgage applications are at a 22-year low, and the market is not expected to rebound soon as the Federal Reserve raises rates. Automation can reduce costs, improve efficiency, and retain staff during downturns, while also speeding up loan origination and keeping banks competitive.
The Federal Reserve's real-time payment system FedNow is scheduled to launch next year, yet industry insiders expect that it may take many more years for U.S. businesses and consumers to rely on widespread instant payments. This article explores how FedNow catches up with pioneers like China, its competition and cooperation with the private RTP network, the participation incentives for small and medium-sized banks, pricing and interoperability challenges, and the lack of fraud prevention.
The Federal Reserve's FedNow real-time payments system is scheduled to launch next year, aiming to modernize the U.S. payments system by enabling instant bank-to-bank transactions. However, industry professionals caution that ubiquitous instant payments may take years to achieve. The U.S. trails countries like China, India, and Brazil in real-time payments adoption, capturing only $1.35 billion in macroeconomic benefits compared to China's $18.65 billion. FedNow will compete with The Clearing House's RTP Network, which has seen slow uptake since 2017. FedNow aims to engage thousands of small banks and credit unions that have been wary of RTP. The system will allow transactions up to $500,000, 24/7/365. Despite partnerships with 80 financial institutions and 40 service providers, challenges remain, including interoperability with other systems, fraud protection concerns, and resistance from big banks. If successful, FedNow could triple U.S. economic benefits from real-time payments by 2026.
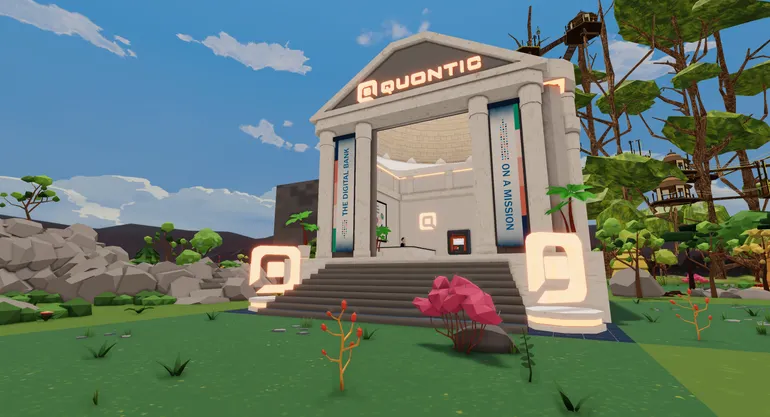
With JPMorgan Chase opening a virtual lounge in Decentraland and Quontic Bank establishing a metaverse outpost, the banking industry is witnessing a wave of metaverse expansion. This article analyzes the first-mover strategies, differentiated paths, and core challenges such as identity management and regulatory compliance faced by financial institutions.
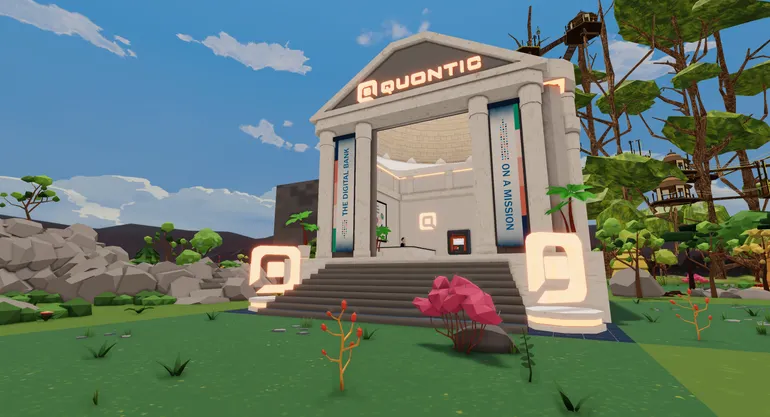
JPMorgan Chase and Quontic Bank are among the first banks to establish a presence in the metaverse, with JPMorgan launching a virtual lounge in Decentraland and Quontic opening an outpost there. The metaverse, seen as a $1 trillion market opportunity, offers new interaction models but raises regulatory and security questions. Other banks like HSBC and BofA are also exploring virtual worlds for customer engagement and training. Experts advise banks to align metaverse strategies with their overall business goals and target demographics.
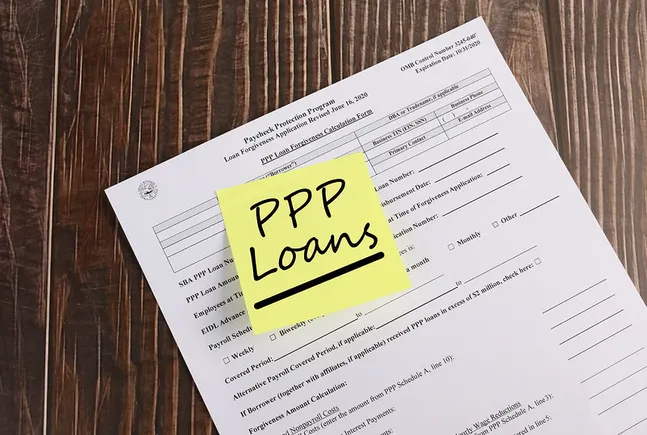
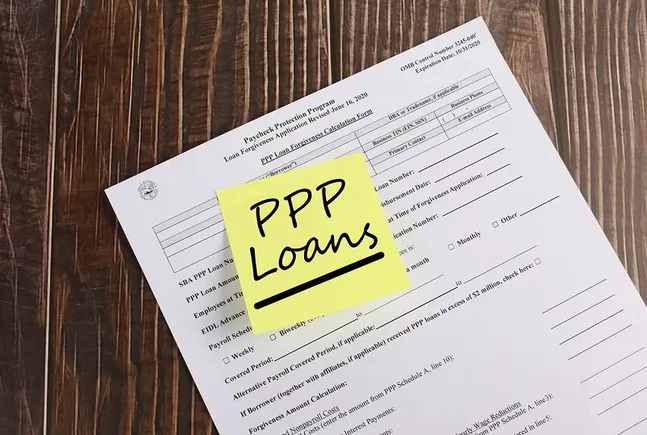
The Paycheck Protection Program (PPP) delivered nearly $800 billion in forgivable loans to businesses during the pandemic. Two years later, lenders and experts reflect on the program's remarkable speed, its acceleration of digital banking, the rise of fintech participation and subsequent fraud scrutiny, and the SBA's next steps amid calls for reform and lingering inequities.
Global financial institutions are preparing for the economic impact of Western sanctions on Russia. The United States imposed sanctions after the 2014 Crimea crisis, and now, in response to Russia's further actions in Ukraine, the U.S. and its allies have escalated sanctions again, but Russia has established protective measures and may use cryptocurrencies to circumvent them.
Global financial institutions are preparing for economic shocks as Western nations impose sanctions on Russia for its aggression in Ukraine. Banks play a crucial role in enforcing sanctions but expose themselves to consequences. The US, UK, and EU have targeted Russian banks, oligarchs, and sovereign debt. The US has not yet blocked Russia from SWIFT, and cryptocurrency may help Russia evade sanctions. European banks have greater exposure to Russia than US banks. Russia's full-scale invasion of Ukraine has prompted Western powers to prepare even stricter sanctions, potentially targeting major banks like Sberbank and VTB.